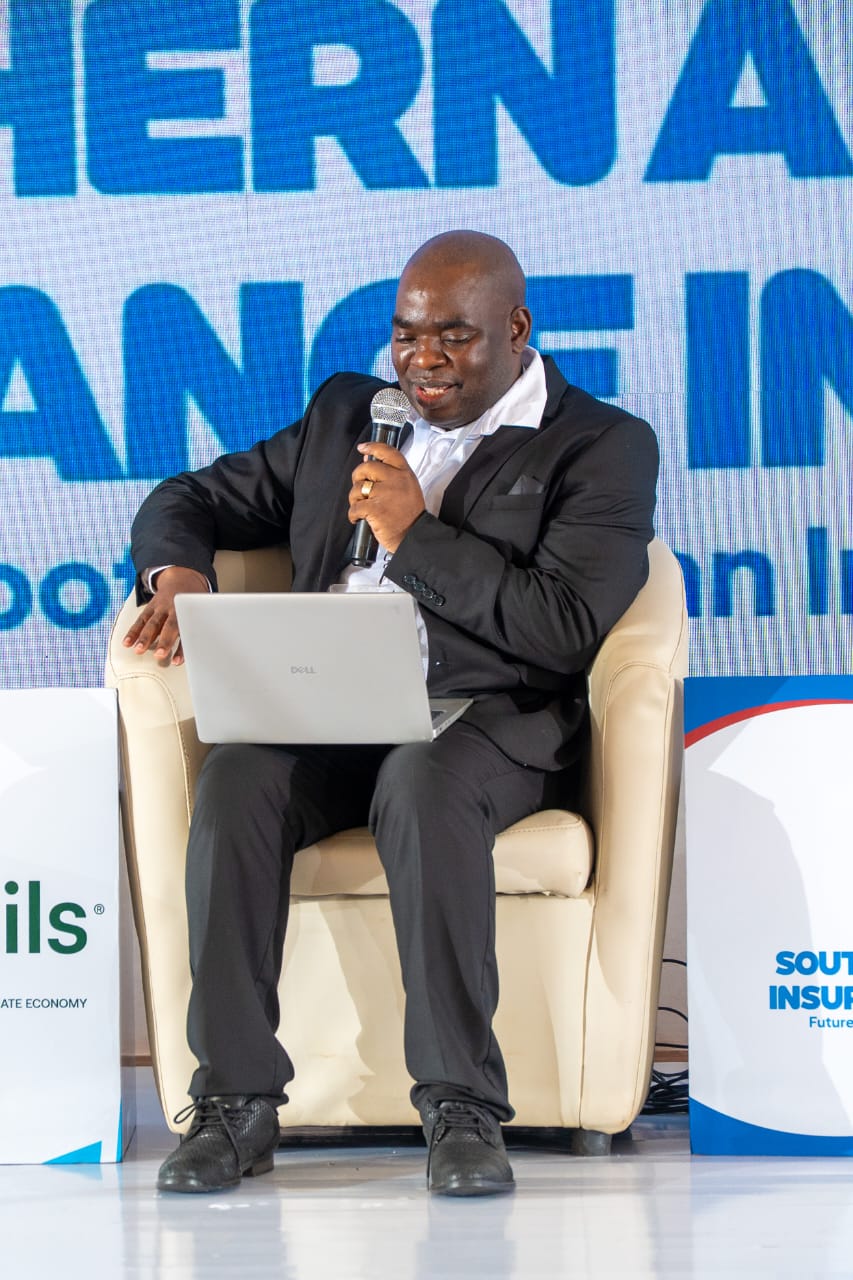
Dr Kennedy Chengeta, co-founder of KaribuTech AI
Nelson Gahadza
VICTORIA FALLS: Insurance companies across Southern Africa must move beyond traditional business models, invest in data-driven technology and strengthen their capacity to withstand economic and climate shocks if they are to remain competitive in an increasingly uncertain business environment.
Dr Kennedy Chengeta, co-founder of KaribuTech AI, told delegates at the Southern Africa Insurance Indaba 2026 that insurance executives needed to make deliberate strategic decisions around growth, technology and survival, warning that companies which failed to adapt risked losing customers, capital and market relevance.
In outlining what insurance leaders must prioritise as they prepare for 2030, Chengeta challenged insurers to abandon practices that undermine profitability and innovation, including price wars, excessive dependence on funeral products, paper-based claims processing and technology projects that lack clear business objectives.
He argued that the industry’s future would depend on its ability to identify new customer segments, build effective distribution partnerships, modernise its operations and maintain public trust while adopting emerging technologies.
Under his proposed strategic framework, insurers should concentrate on reaching underserved markets profitably, developing paperless and AI-assisted operations, and protecting their businesses against financial, technological and environmental disruptions.
Chengeta identified five immediate priorities for insurance executives, beginning with selecting a specific growth segment and establishing a distribution partnership capable of reaching customers who remain outside the formal insurance market.
Rather than attempting to serve every possible market simultaneously, insurers should identify segments where they can build a competitive advantage and develop products that respond to customers’ actual needs and payment capabilities.
He highlighted opportunities among informal traders, low-income households, smallholder farmers and diaspora-funded families, which remain potential sources of growth for an industry seeking to expand insurance penetration.
Distribution partnerships with telecommunications companies, banks, retailers and mobile money operators were also identified as essential to reaching these markets.
The approach would allow insurers to sell products through platforms and channels customers already use, reducing distribution costs while making insurance more accessible.
Chengeta also urged insurers to address weaknesses in their data management systems, arguing that meaningful digital transformation and artificial intelligence adoption would remain difficult without reliable and well-organised customer information.
He proposed establishing a single customer view across insurance products, supported by clearly designated data owners and secure systems that allow information to be used responsibly.
The emphasis on data comes as insurers increasingly consider artificial intelligence for underwriting, claims assessment, fraud detection, customer service and pricing.
However, Chengeta cautioned against adopting AI simply because it is becoming an industry trend, calling on companies to demonstrate measurable business benefits before committing substantial resources to technology projects.
He recommended that insurers identify one AI application, assign it a responsible executive, establish a measurable performance target and assess its results within 90 days.
Projects that demonstrate value could then be expanded, while those that fail to deliver should be discontinued.
He further argued that AI investment should be treated as an enterprise-wide strategic priority rather than an isolated information technology expense.
The presentation also placed considerable emphasis on the need for insurers to strengthen their resilience against shocks that could threaten their ability to meet policyholder obligations.
Chengeta identified foreign currency volatility, climate-related disasters, cyberattacks, system outages and reduced reinsurance capacity among the major risks that insurance companies must prepare for.
He called on boards to conduct regular stress tests covering currency movements, climate events, technology disruptions and changes in reinsurance capacity.
A key recommendation was that insurers should ensure their assets and liabilities are appropriately matched by currency to minimise exposure arising from exchange rate movements.
This is particularly important in markets where insurers operate across multiple currencies while facing challenges in maintaining the value of long-term policyholder obligations.
He also called for stronger regional reinsurance arrangements and improved catastrophe risk modelling to enable more risks to be retained within African markets.
The presentation proposed that insurers progressively strengthen their internal capacity to understand and manage climate-related exposures, including through parametric insurance products and partnerships with reinsurers.
On technology resilience, companies were encouraged to establish tested recovery arrangements, maintain offline backups and develop exit plans for critical technology vendors to reduce dependence on systems that could become unavailable.
Chengeta’s proposed framework envisages insurers being able to recover critical systems within four hours, with boards testing at least five shock scenarios annually.
Beyond the three strategic priorities, he identified trust and governance as essential conditions for the industry’s transformation.
He argued that the increasing use of AI in decisions affecting underwriting, pricing and claims would require stronger accountability, transparency and safeguards against unfair treatment of customers.
Insurers should therefore ensure that AI-driven decisions are explainable, contestable and lawful, with customers retaining access to human intervention where automated decisions affect their interests.
He also called for stronger cybersecurity and data protection measures, particularly as insurers handle sensitive customer information, including identification documents, health records and financial details.
The presentation outlined several risks requiring board-level attention, including deepfake-related fraud, ransomware, customer data breaches, AI bias, technology vendor failures and the migration of skilled professionals.
Chengeta also urged insurance companies to invest in developing the skills of their employees and boards to ensure they can effectively oversee emerging technologies and changing business risks.
On the regulatory front, he called for a more supportive framework to enable responsible innovation without compromising consumer protection and financial stability.
Among his proposals was the establishment of a professional framework for artificial intelligence specialists, modelled on the actuarial profession, with accredited professionals working alongside insurers and regulators.
He proposed that every insurer should appoint an AI officer responsible for overseeing the use of artificial intelligence, supported by annual AI sign-off reports to company boards and the Insurance and Pensions Commission (IPEC).
He further recommended that IPEC develop guidance on AI use, introduce model-risk standards and establish regulatory sandboxes where insurers could test new products and technologies under appropriate supervision.
Other proposals included common industry standards for fair AI applications, improved sharing of fraud and deepfake information, and stronger collaboration between regulators and government agencies to facilitate identity verification through official registries.
He also called for regulatory clarity around cloud computing, data transfers and cross-border insurance operations, alongside harmonised rules across the Southern African Development Community.
For regulators, Chengeta proposed accelerating approval processes for microinsurance and mobile-based products, introducing clear guidelines for embedded insurance and developing frameworks for index-based and parametric insurance.
He stressed that innovation should be accompanied by regulatory certainty, particularly as insurers increasingly collaborate with technology companies, banks and telecommunications operators.
The presentation also outlined a practical roadmap for insurance executives, recommending that newly appointed chief executives use their first 100 days to understand their businesses before implementing major changes.
The process should begin with consultations with customers, brokers, regulators and reinsurers, followed by assessments of solvency, foreign currency exposure, profitability, data systems and operational weaknesses.
Executives should then identify a growth segment, appoint responsible leaders for data and AI initiatives, agree on key risk scenarios and introduce measurable projects.
Chengeta cautioned against rushing into large-scale core-system replacements, restructuring businesses before understanding their challenges or announcing AI initiatives without clear performance targets.
Ultimately, his message was that the insurance industry should not view growth, technology and survival as competing priorities but as interconnected elements of a sustainable business strategy.
Growth should provide the resources to fund technological transformation, technology should reduce operating costs and improve risk management, while resilience should protect the gains made through expansion.
The Southern Africa Insurance Indaba 2026 brought together insurance executives, regulators and industry stakeholders in Victoria Falls to examine the challenges and opportunities shaping the region’s insurance sector.


